Robot Certification Market Research Report
Global Market Size, Share & Trends Analysis Report, 2026-2035
Segmentation Analysis By Certification Type: By Robot Type: By End-use Industry: By Service Type: By Certification Body: By Region and Industry Forecast
1. Market Summary:
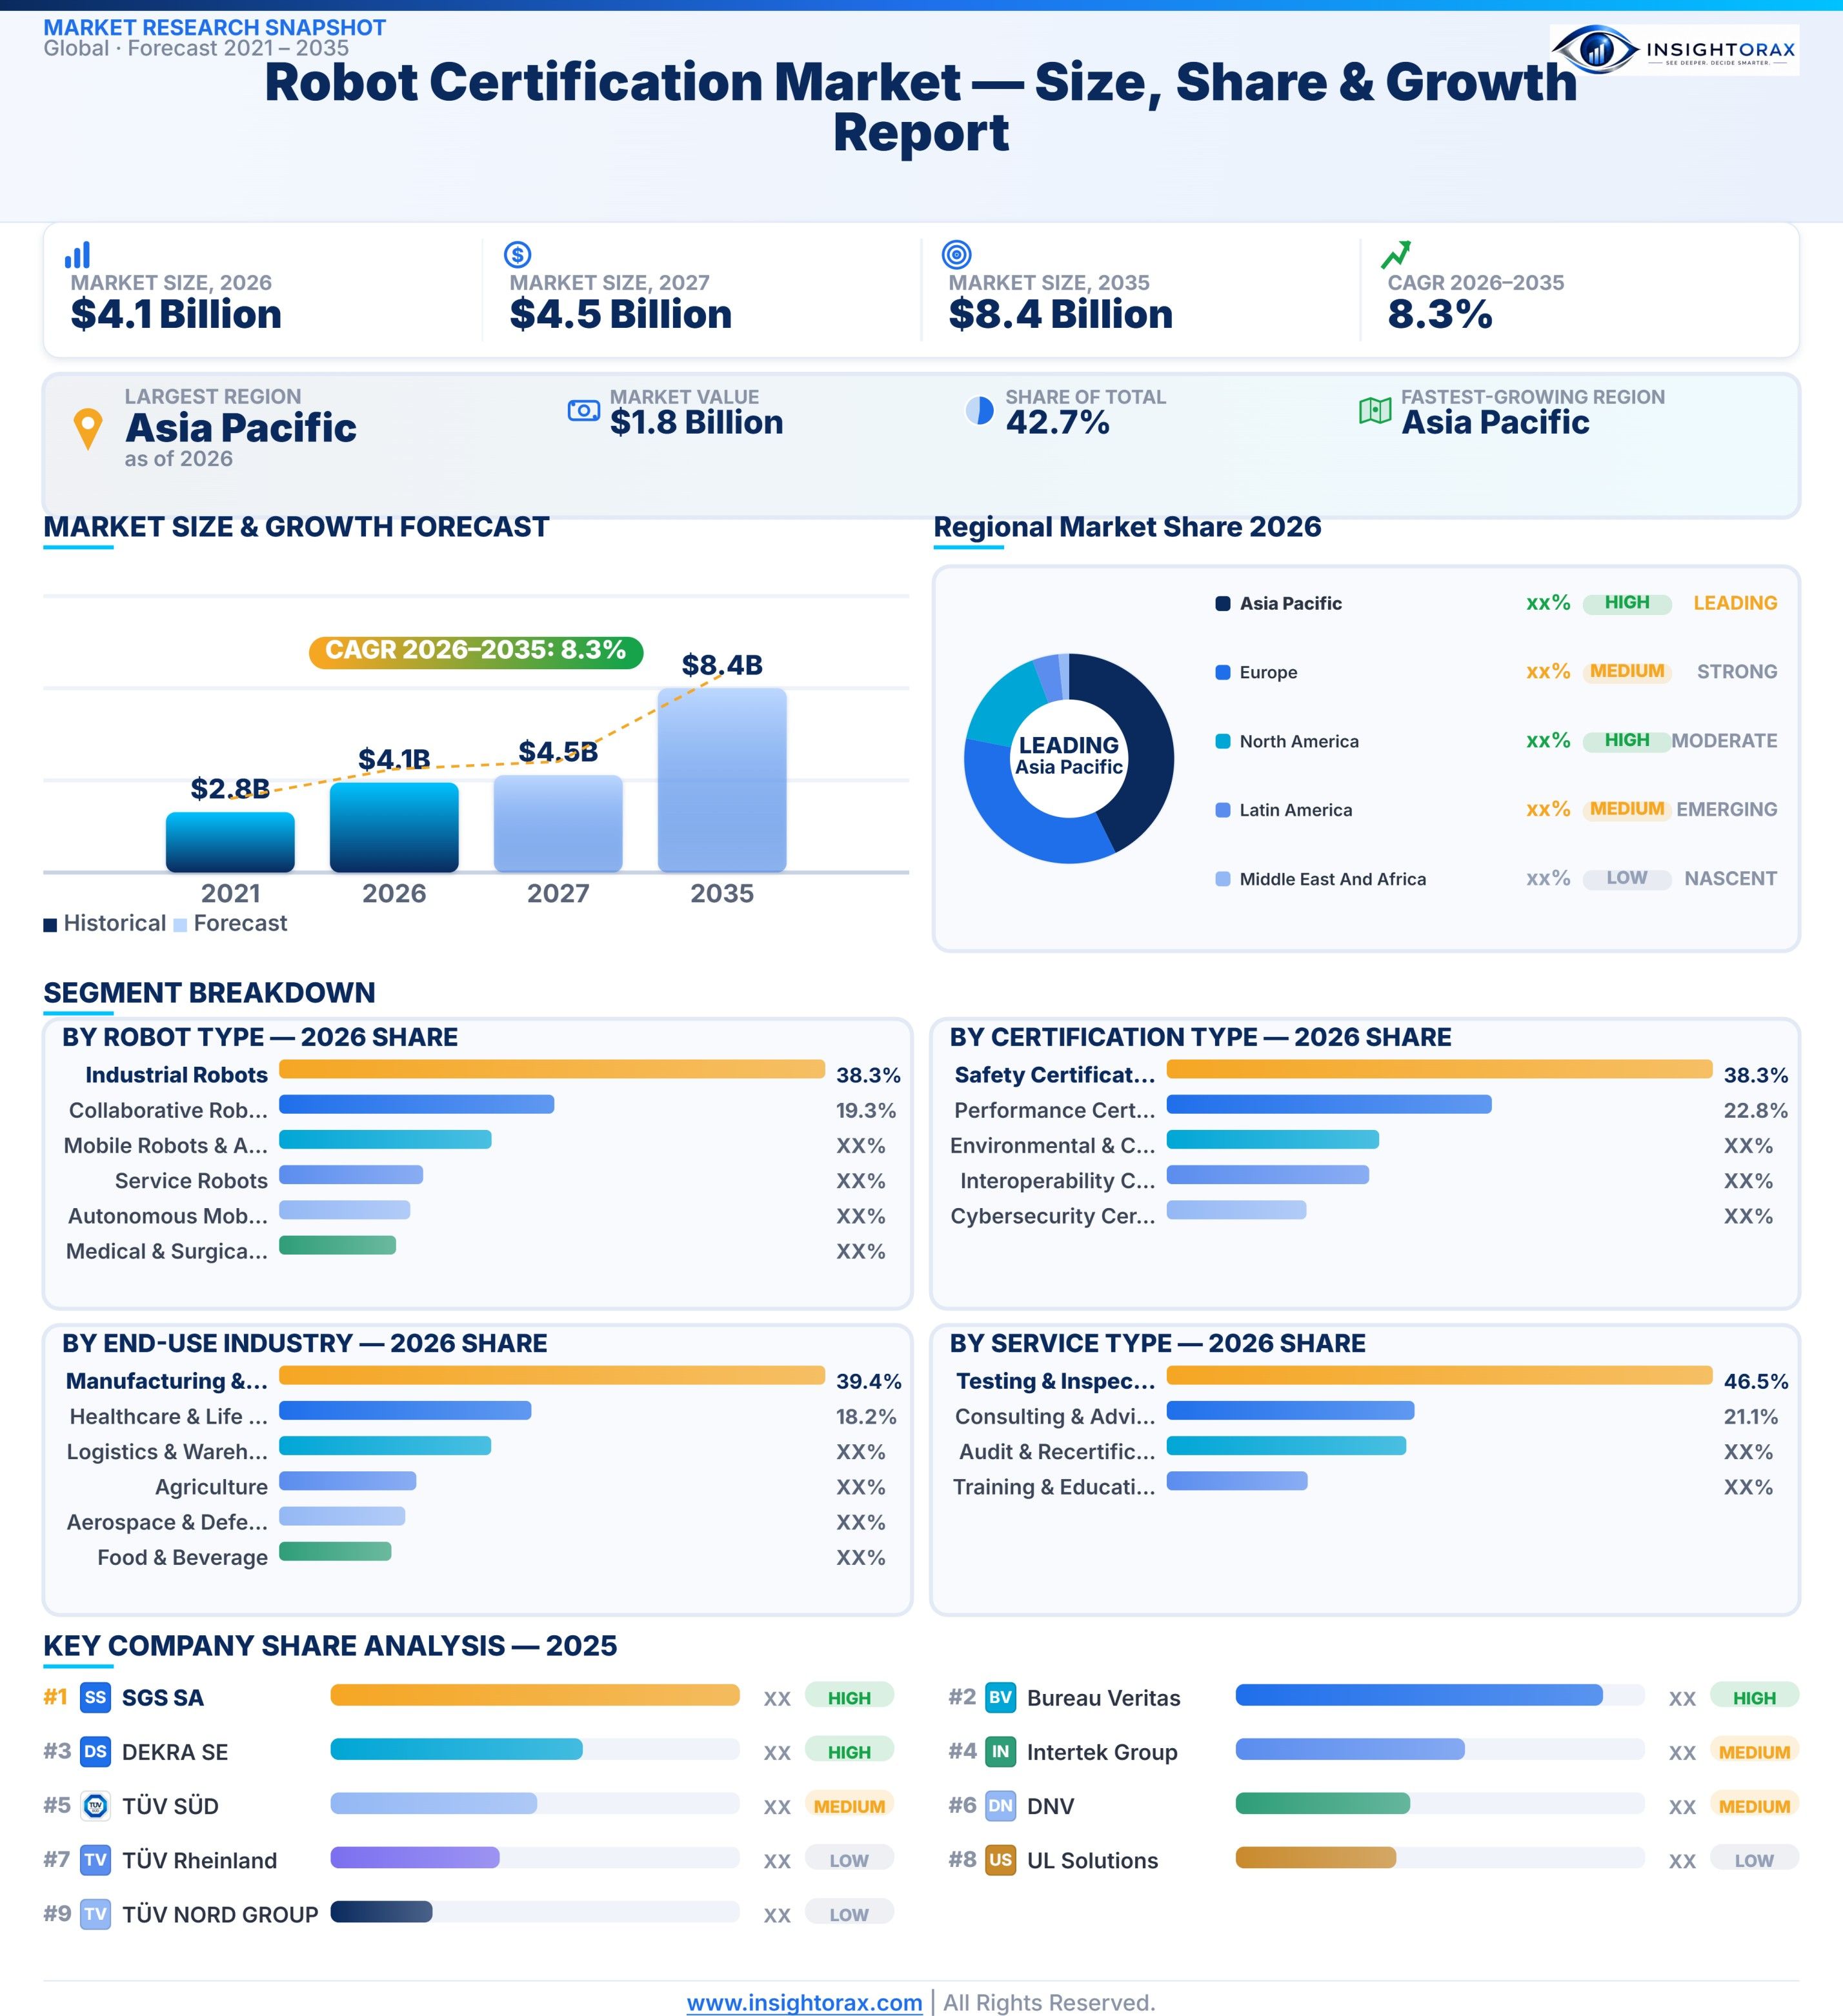
According to data analyzed by Insightorax, the global robot certification market size was valued at USD 4.1 billion in 2026 and is projected to grow from USD 4.4 billion in 2027 to USD 8.4 billion by 2035, registering a CAGR of 8.3% during the 2026–2035 forecast period. Asia Pacific accounted for the largest revenue share of 42.3% in 2026. Market growth is supported by the rapid adoption of industrial, collaborative, autonomous, and service robots across manufacturing, logistics, healthcare, automotive, and other sectors. Increasing workplace safety requirements, evolving international standards, and stronger regulatory compliance are encouraging manufacturers and system integrators to obtain certification before deployment. Demand is further strengthened by human-robot collaboration, AI-enabled robotics, cross-border market access requirements, and the need to validate robot safety, reliability, and performance.
2. Market Overview:
The Robot Certification Market refers to the ecosystem of testing, inspection, assessment, and certification services used to verify that robotic systems comply with applicable safety, performance, quality, and regulatory requirements. It covers certification activities for industrial robots, collaborative robots, mobile robots, autonomous robotic systems, and specialized robots used across manufacturing, logistics, healthcare, automotive, electronics, and other industries. The market supports organizations in demonstrating that robotic equipment meets established technical standards before deployment or during operational use.
The market scope includes robot safety certification, functional and performance testing, electromagnetic compatibility assessment, risk assessment, inspection, compliance evaluation, and documentation. Key components include certification bodies, testing laboratories, inspection organizations, robot manufacturers, system integrators, and end users. Certification requirements can address machine safety, human-robot interaction, electrical safety, software-related functions, cybersecurity considerations, and operational reliability. The market also encompasses certification services for individual robots, robotic systems, components, and integrated automation environments.
3. Market Size & Forecast:
The Robot Certification Market has evolved alongside the increasing use of robotics in industrial automation. Early certification activities primarily focused on machine safety, electrical compliance, and basic performance requirements for industrial robots. As robotic technologies became more sophisticated, certification frameworks expanded to address collaborative operation, autonomous functions, integrated robotic systems, and increasingly complex operating environments.
The market is currently expanding as manufacturers and end users place greater emphasis on workplace safety, regulatory compliance, reliability, and risk reduction. Future growth is expected to remain strong as robotics adoption spreads across manufacturing, logistics, healthcare, automotive, electronics, and other sectors. The development of collaborative and autonomous robots, stricter safety standards, cross-border regulatory requirements, and growing demand for validated robotic performance will encourage more organizations to seek independent testing and certification. Increasing integration of AI and advanced sensing technologies will further strengthen the need for comprehensive certification services.
Key Market Trends & Insights
- By robot type: Industrial Robots segment dominated the market with a 38.3% share in 2026.
- By certification type: Safety Certification segment led the market in terms of share, accounting for 38.3% in 2026.
- By end-use industry: Manufacturing & Automotive segment commanded the largest market share at 39.4% in 2026.
- By service type: Testing & Inspection segment accounted for the highest market share of 46.5% in 2026.
- By certification body: Third-party Certification Agencies segment maintained a leading position in the market, holding a 62.3% share in 2026.
Regional Highlights
- Largest regional market: Asia Pacific (42.2% revenue share, 2026)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2035)
- By country: China held the largest market share 16.0% in 2026
Market Size & Forecast
- Market size in 2026: USD 4.1 Billion
- Estimated market size in 2027: USD 4.5 Billion
- Projected market size by 2035: USD 8.4 Billion
- CAGR (2026-2035): 8.3%
4. Market Drivers, Restraints & Opportunities:
The Robot Certification Market is driven by the rapid adoption of industrial and collaborative robots, increasing workplace safety requirements, stricter regulatory standards, and growing demand for reliable automated systems. Manufacturers and end users are placing greater emphasis on risk assessment, compliance validation, and performance verification as robots become more integrated into critical production and service environments. Expansion of robotics across automotive, electronics, logistics, healthcare, and manufacturing is also increasing certification requirements. However, high certification costs, complex testing procedures, evolving technical standards, limited awareness among smaller businesses, and differences in regulatory requirements across countries can restrain market development.
Opportunities are emerging from the expansion of autonomous and collaborative robotics, AI-enabled systems, and robotic applications in new industries. Growing international deployment of robots is creating demand for standardized certification and cross-border compliance services. Certification providers can also benefit from digital testing technologies, remote assessment capabilities, specialized safety evaluations, cybersecurity verification, and lifecycle certification services as organizations seek continuous validation throughout robotic system deployment and operation.
5. Market Trends:
The Robot Certification Market is increasingly shaped by the adoption of collaborative robots, autonomous mobile robots, and AI-enabled robotic systems, which require broader safety and performance assessments than conventional industrial robots. Recent developments in international robot safety standards are encouraging manufacturers and integrators to strengthen risk assessment, functional safety, human-robot interaction testing, and system-level compliance. Digital inspection, simulation-based testing, and remote assessment are also gaining attention as certification providers seek faster and more flexible evaluation processes. Growing emphasis on cybersecurity and software reliability is further expanding certification requirements for connected and intelligent robotic systems.
Regionally, Asia-Pacific remains a major hub for robotics deployment, particularly across manufacturing-intensive economies, supporting demand for certification and compliance services. Europe continues to emphasize stringent machinery safety and regulatory compliance, while North America is experiencing demand from automation, logistics, and advanced manufacturing. Emerging markets are also gradually increasing certification adoption as industrial automation expands.
6. Technology Landscape:
The technology landscape is evolving as robotic systems incorporate advanced sensors, machine vision, artificial intelligence, connectivity, and increasingly autonomous functions. These technologies enable robots to perceive environments, make decisions, navigate dynamic workplaces, and interact more closely with people. Certification processes are consequently expanding beyond traditional mechanical and electrical safety assessments toward validation of sensing systems, safety-related controls, software functions, human-robot interaction, and integrated system performance. Simulation and digital testing tools are also supporting more efficient evaluation before physical deployment.
Connected robots are increasing the importance of cybersecurity, data integrity, and software reliability, particularly in networked industrial and logistics environments. Collaborative and mobile robotics are driving demand for application-specific testing because their operating conditions differ from fixed industrial equipment. Advances in AI-enabled robotics may further increase the need for structured validation as system behavior becomes more complex. These developments are encouraging certification providers to adopt digital assessment methods and broader, system-level evaluation approaches.
7. Robot Certification Market Segmentation Analysis:
8. By Certification Type:
Safety Certification held the leading position in the Robot Certification Market, accounting for 38.3% market share in 2026. It plays a crucial role in ensuring that robotic systems meet established safety requirements, protect workers, and operate reliably in industrial and commercial environments. Increasing automation across manufacturing, automotive production, and logistics is driving demand for safety assessments and compliance verification. Certification evaluates potential hazards, emergency stop mechanisms, protective systems, and operational risks associated with robotic equipment. As robots become more integrated into collaborative workplaces, safety validation is increasingly important for manufacturers and end users. Safety Certification supports regulatory compliance, operational reliability, and workplace protection, making it an essential component of the robotics ecosystem.
Performance Certification represented the second-largest category, with a 22.8% market share in 2026. It evaluates robotic systems against specified operational requirements, including accuracy, efficiency, repeatability, and functional reliability. Demand is supported by industries seeking consistent performance and dependable automation outcomes. Interoperability Certification, Cybersecurity Certification, and Environmental & Compliance Certification also contribute to the market by addressing system compatibility, digital security, and environmental or regulatory requirements. These certification categories are becoming increasingly relevant as robots incorporate connected technologies, advanced control systems, and automated decision-making capabilities. Together, these services help establish confidence in robotic technologies, facilitate industrial adoption, and support compliance across diverse operating environments.
9. By Robot Type:
Industrial Robots accounted for the highest share of the Robot Certification Market by robot type, representing 38.3% market share in 2026. Their extensive deployment across manufacturing facilities, automotive assembly lines, electronics production, and material-handling operations supports sustained demand for certification services. These robots perform repetitive, high-precision, and physically demanding tasks, making safety validation and performance verification essential for reliable operation. Certification helps manufacturers demonstrate compliance with applicable technical requirements, assess operational risks, and maintain consistent production standards. Increasing automation, factory modernization, and the integration of robotic systems into complex production environments reinforce the importance of certification. Industrial Robots therefore represent a significant application area for testing, inspection, and regulatory conformity services.
Collaborative Robots (cobots) held the second-largest position, with a 19.3% market share in 2026. Their growing adoption in workplaces where humans and robots operate in close proximity creates demand for safety assessments, operational validation, and compliance verification. Cobots are used in assembly, inspection, packaging, and material handling, particularly where flexible automation is required. Mobile Robots & AGVs, Service Robots, Medical & Surgical Robots, and Autonomous Mobile Robots (AMRs) also contribute to certification demand. Their applications span logistics, healthcare, commercial services, and autonomous material transportation. As robotic technologies expand into diverse operating environments, certification supports risk management, system reliability, and compliance with relevant standards, helping organizations integrate automated solutions into existing workflows.
10. By End-use Industry:
Manufacturing & Automotive represented the leading end-use industry, accounting for 39.4% market share in 2026. Extensive robotic deployment across vehicle assembly, welding, painting, component handling, and precision manufacturing creates sustained demand for certification services. Manufacturers require safety assessments, performance verification, and compliance validation to ensure that robotic systems meet operational requirements. The growing use of automated production lines and advanced industrial robotics further increases the importance of independent testing and certification. Certification helps organizations address workplace safety, maintain production consistency, and verify the reliability of automated equipment. As manufacturers modernize facilities and integrate increasingly sophisticated robotic technologies, certification remains an important part of industrial automation deployment and operational risk management.
Healthcare & Life Sciences held the second-largest position, with an 18.2% market share in 2026. Demand is supported by the adoption of robotic systems in surgical procedures, laboratory automation, medical assistance, and pharmaceutical operations. Certification helps assess the safety, functionality, and reliability of robotic equipment used in sensitive healthcare environments. Logistics & Warehousing, Aerospace & Defense, Food & Beverage, and Agriculture also contribute to market demand. These industries use robots for material transportation, precision operations, inspection, packaging, and specialized tasks. Their certification requirements vary according to operating conditions, safety considerations, and applicable regulations. The expansion of robotics across diverse industries reinforces the significance of certification in supporting reliable automation and compliance.
11. By Service Type:
Testing & Inspection accounted for the largest share of the service-type segment, representing 46.5% market share in 2026. These services assess robotic systems against applicable safety, performance, and technical requirements before deployment and during operational evaluation. Testing activities can include functional verification, mechanical assessments, safety testing, and system performance analysis. Increasing adoption of industrial robots, collaborative systems, and autonomous technologies is supporting demand for structured testing procedures. Manufacturers and end users rely on inspection services to identify potential defects, verify conformity, and improve confidence in robotic equipment. As automation expands across manufacturing, healthcare, and logistics, Testing & Inspection remains a fundamental service category supporting compliance, operational reliability, and safe integration of robotic systems.
Consulting & Advisory represented the second-largest category, with a 21.1% market share in 2026. These services help robotics manufacturers and users understand certification requirements, identify applicable standards, prepare technical documentation, and address compliance gaps. Organizations increasingly seek specialized guidance as robotic systems become more complex and certification requirements vary across applications and jurisdictions. Training & Education and Audit & Recertification also contribute to the service landscape. Training supports awareness of certification procedures, safety requirements, and technical standards, while audits and recertification help organizations maintain conformity throughout the operational lifecycle. Together, these services support effective certification planning, continued compliance, and the responsible deployment of robotic technologies across industrial and commercial environments.
12. By Certification Body:
Third-party Certification Agencies held the leading position among certification bodies, accounting for 62.3% market share in 2026. These agencies provide independent testing, conformity assessment, and certification services for robotic systems across multiple industries. Their role is particularly important for manufacturers seeking external verification of safety, performance, and compliance with applicable standards. Demand is supported by increasing automation, expanding international supply chains, and the need for credible assessments of robotic equipment. Independent certification can help organizations demonstrate conformity to customers, regulators, and business partners. As robotic systems become more sophisticated and widely deployed, third-party agencies remain central to the certification ecosystem by providing specialized technical expertise and structured evaluation services.
OEM Self-certification represented the second-largest category, with a 17.8% market share in 2026. This approach involves original equipment manufacturers conducting internal assessments and verification activities to demonstrate that their robotic products meet specified requirements. It can support product development, internal quality assurance, and compliance documentation, subject to applicable regulatory frameworks and certification requirements. Government & Regulatory Bodies and International Standards Organizations also contribute to the certification landscape through regulatory oversight, standards development, and conformity frameworks. Their activities help establish consistent technical expectations and clarify requirements for robotic technologies. The interaction between independent agencies, manufacturers, public authorities, and standards organizations supports certification processes, strengthens accountability, and facilitates the adoption of robotic systems across different markets.
13. Regional Analysis:
Asia Pacific accounted for 42.3% of the market in 2026, representing the largest regional contribution. The region's extensive manufacturing base, expanding industrial automation, and increasing adoption of robotic technologies support demand for certification services. Countries such as China, Japan, South Korea, and India contribute to the robotics ecosystem through manufacturing, automotive production, electronics, and logistics operations. Industrial robots, collaborative robots, and autonomous mobile robots create requirements for safety validation, performance testing, and regulatory compliance. Growing integration of connected robotic systems also increases the importance of cybersecurity and interoperability assessments. Certification helps manufacturers verify operational reliability, meet applicable technical requirements, and support the deployment of automated equipment. Expanding industrial capabilities and technological development reinforce the region's significance in the global certification landscape.
North America represented 16.2% of the market in 2026. Demand for certification services is supported by industrial modernization, advanced manufacturing, and the adoption of robotics across automotive production, healthcare, aerospace, and logistics. The United States and Canada utilize robotic technologies in applications requiring operational reliability, workplace safety, and technical compliance. Industrial automation, collaborative robotics, and autonomous material-handling systems contribute to the need for testing, inspection, and certification. Increasing connectivity between robotic equipment and digital infrastructure also creates demand for cybersecurity assessments and interoperability verification. Certification enables manufacturers and end users to demonstrate conformity with relevant standards and address operational risks. The region's established technology ecosystem and continued automation investments support its importance in the international certification industry.
Europe accounted for 35.7% of the market in 2026, making it a significant regional contributor. The region's established automotive, industrial machinery, aerospace, and manufacturing sectors generate demand for robotic safety assessments, performance verification, and compliance services. Germany, France, Italy, and other European economies employ robotic systems across production, assembly, inspection, and material-handling applications. Industrial automation and collaborative robotics increase the need for systematic safety validation and conformity assessment. Regulatory requirements and technical standards also influence demand, particularly where robotic equipment operates alongside workers or within interconnected production environments. Testing and inspection services help manufacturers demonstrate compliance, maintain equipment reliability, and support market access. Europe's industrial expertise, engineering capabilities, and emphasis on standardized technical requirements sustain its importance in the global certification landscape.
Middle East & Africa represented 1.7% of the market in 2026. Demand for certification services is associated with the gradual adoption of robotics across manufacturing, logistics, healthcare, infrastructure, and industrial operations. Automation initiatives and investments in industrial modernization create opportunities for robotic testing, safety verification, and compliance assessment. In the Middle East, applications include material handling, industrial operations, and specialized service environments. African markets are exploring automation across manufacturing, warehousing, agriculture, and healthcare. Certification supports the evaluation of equipment reliability, operational safety, and conformity with applicable requirements. As organizations introduce robotic systems into existing facilities, testing and advisory services can help address technical and operational considerations. The region's developing automation ecosystem contributes to the broader geographic expansion of certification services.
Latin America accounted for 4.1% of the market in 2026. Regional demand is supported by industrial automation, manufacturing modernization, and the adoption of robotics across automotive production, food processing, logistics, and agricultural operations. Brazil and Mexico contribute to the region's industrial activity and deployment of automated equipment. Robotic applications in assembly, packaging, inspection, and material handling create requirements for safety assessments, performance testing, and compliance verification. Organizations integrating robotic systems into production facilities increasingly need technical evaluations to support reliable operation and workplace safety. Certification services also help manufacturers and equipment suppliers address applicable standards and operational requirements. As automation expands across industrial and commercial environments, certification remains relevant to equipment validation, risk management, and the development of a more integrated regional robotics ecosystem.
14. Competitive Landscape:
Competition in the Robot Certification Market is shaped by testing laboratories, inspection organizations, certification bodies, and specialized safety assessment providers. Companies differentiate through technical expertise, accreditation, faster testing cycles, broader service portfolios, and capabilities covering industrial, collaborative, mobile, and specialized robotic systems. Geographic expansion is supported by establishing regional testing capabilities and serving manufacturers seeking compliance across multiple jurisdictions. Partnerships with robot manufacturers, system integrators, research institutions, and industry organizations help providers strengthen technical capabilities and expand customer access.
Leading providers increasingly adopt digital inspection, simulation, automated testing, and remote assessment technologies to improve efficiency and address increasingly complex robotic systems. Businesses are also expanding services to cover functional safety, cybersecurity, software validation, and human-robot interaction. Relevant certifications and accreditation strengthen market credibility, while strategic collaborations and integrated compliance services help retain customers. Organic inputs are not applicable to this market; competitive strategies instead focus on technological expertise, regulatory knowledge, service quality, international coverage, and specialized testing capabilities.
15. Key Robot Certification Company Insights:
The Robot Certification Market features established testing, inspection, and certification organizations competing through technical expertise, accredited laboratories, regulatory knowledge, global reach, and specialized robotics services. UL Solutions provides testing and certification for industrial, collaborative, mobile, consumer, and commercial robots, while TÜV SÜD supports robotic safety testing, product certification, and auditing across the product lifecycle. TÜV Rheinland provides services for industrial, collaborative, autonomous mobile, and service robots, covering testing, functional safety, and international conformity requirements. Other prominent participants include SGS, Intertek, Bureau Veritas, DEKRA, TÜV NORD, CSA Group, DNV, Applus+, Eurofins, Kiwa, Nemko, Element Materials Technology, and MET Laboratories.
Competition increasingly centers on service breadth, certification speed, international market access, and the ability to address complex robotic technologies. Providers are expanding capabilities in functional safety, human-robot interaction, cybersecurity, software validation, performance testing, and risk assessment. Partnerships with robot manufacturers, system integrators, research organizations, and industry bodies support technical development and customer acquisition. Geographic expansion through regional laboratories and conformity-assessment networks enables companies to serve manufacturers entering multiple markets. Digital inspection, simulation-based assessment, and remote testing are also becoming important differentiators as autonomous, collaborative, and connected robots increase certification complexity.
· TÜV SÜD – Provides robotics and machinery safety assessment, functional-safety services, testing, inspection and certification. Its positioning is particularly strong in industrial automation, machinery safety and international conformity assessment.
· TÜV Rheinland – Offers testing, inspection and certification for robotics, machinery and automated systems, with expertise spanning functional safety, electrical safety, EMC and regulatory market access. Its global TIC network supports multinational robot manufacturers.
· TÜV NORD GROUP – Focuses on industrial machinery safety, testing, inspection and certification. Its capabilities support robot manufacturers and integrators seeking compliance with European and international safety requirements.
· SGS SA – Provides robotic product testing and certification covering safety, performance, cybersecurity and regulatory compliance. Its broad global laboratory and TIC infrastructure supports robot manufacturers entering multiple markets.
· Bureau Veritas – Provides product testing, inspection and certification across industrial technologies. Its strengths include conformity assessment, regulatory compliance and international market access for equipment manufacturers.
16. Key Robot Certification Companies:
· TÜV Rheinland
· TÜV NORD
· SGS SA
· Bureau Veritas
· Intertek Group
· UL Solutions
· DNV
· DEKRA SE
· CSA Group
· NSF International
· Eurofins Scientific
· RINA S.p.A.
· Applus+
· Element Materials Technology
· Southwest Research Institute (SWRI)
· MET Laboratories
· exida
· SIRA Certification Service
· Certification Europe
17. Recent Developments:
In 2025, ISO published revised editions of ISO 10218-1 and ISO 10218-2, updating safety requirements for industrial robots and robotic applications. The revisions address areas including robot safety, risk reduction, functional safety, and integration requirements, creating new compliance considerations for manufacturers, integrators, and certification providers.
· March 4, 2026 — UL Solutions: Certified Simbe’s Tally autonomous mobile robot under UL 3300 after it passed more than 40 safety tests, supporting safe deployment in public-facing retail environments.
· April 21, 2026 — TÜV Rheinland: Reported €2.98 billion revenue in 2025, up 9.7%, reflecting continued international expansion and investment in testing, inspection, certification, and future technologies.
· May 6, 2026 — SGS: Verified DOBOT’s CR 30H collaborative robot series against the cybersecurity requirements of ISO 10218-1:2025, following a February 2026 Verification of Conformity.
· April 9, 2026 — TÜV NORD GROUP: Reported €1.795 billion revenue in 2025, up 6.0%, while emphasizing digitalization, cybersecurity, critical-infrastructure protection, and safety-relevant technology markets.
· April 17, 2026 — DEKRA: Reported €4.4417 billion revenue in 2025, up 3.4%, with continued demand for testing and certification services and further emphasis on technology, digital trust, and safety.
18. Future Outlook:
The Robot Certification Market is expected to maintain a positive growth trajectory as robotics adoption expands across manufacturing, logistics, healthcare, and other automated environments. The publication of updated ISO 10218-1:2025 and ISO 10218-2:2025 standards is increasing the importance of structured safety assessment, risk reduction, and integration compliance. Growing deployment of collaborative, mobile, and connected robots will create opportunities for specialized testing and certification services.
Future opportunities will increasingly center on functional safety, cybersecurity, human-robot interaction, software validation, and digital assessment methods. Certification providers can expand through international conformity services and application-specific testing as manufacturers seek access to multiple markets. However, evolving standards, complex robotic architectures, high assessment costs, and differences among regional regulatory frameworks may create challenges. The need to evaluate increasingly autonomous systems will encourage broader, system-level certification approaches.
19. Methodology Overview
Extensive research from reliable academic sources, industry reports, and publications.
Interviews with industry experts, opinion leaders, and key stakeholders.
Validation of data through top-down and bottom-up approaches.